The Architecture of Fiscal Autonomy
By: Jane Marie F.
For individuals who have successfully built substantial private capital in Europe, the contemporary landscape is no longer just a regulatory burden—it has mutated into an active campaign of asset containment. Between aggressive asset-tax metrics, expanding digital wealth registries, and highly unstable fiscal policies, holding personal tax residency in mainstream Western European states has become an unacceptable structural risk.
To preserve both capital and personal autonomy, those holding significant portfolios are abandoning passive asset management. Instead, they are utilizing Jurisdictional Engineering—the tactical separation of their business operations, personal residencies, and legal structures across multiple sovereign borders. For those navigating these high-stakes conditions, three highly practical, ironclad pathways exist to completely bypass the European fiscal trap.
1. The Fiscal Cap: Switzerland’s Lump-Sum Taxation (Forfait)
For capital holders who value European culture and geographical proximity but refuse to submit their global investment portfolio to arbitrary wealth distribution, Switzerland remains the gold standard through its Lump-Sum Taxation System (Forfait fiscal).
[Global Wealth & Portfolios] ➔ Protected Globally (0% Swiss Tax)
│
[Swiss Living Expenses] ➔ Only This is Taxed
│
[Negotiated Flat Annual Tax]
- The Mechanics: Under this regime, the Swiss government completely ignores an individual’s actual global income, stock dividends, and asset capital appreciation. Instead, they calculate the tax bill based strictly on a “fictitious rental value”—a multiplier of annual living expenses inside Switzerland (such as housing costs, vehicles, and lifestyle maintenance).
- The Practical Application: You negotiate a flat, predictable annual tax amount with a specific Swiss canton upfront. For an individual holding substantial global capital, their tax liability is capped permanently at that flat negotiated figure. Their broader assets continue to compound at a 0% Swiss tax rate, effectively neutralizing the threat of asset-grabbing frameworks like the Dutch Box 3 or the French wealth levies.
2. The Absolute Shield: Italy’s Flat-Tax Option
Introduced explicitly to siphon high-earning residents away from high-tax neighbors, Italy’s specialized Substitute Tax Regime offers unprecedented simplicity and absolute protection for private fortunes.
- The Mechanics: Upon moving your primary tax residency to Italy, you pay a flat, non-indexed fee of €100,000 per year to the Italian government.
- The Practical Application: This single annual payment completely covers and exempts all foreign-sourced income. Whether you generate significant returns across global businesses, foreign real estate portfolios, or offshore investments, your Italian tax obligation is fully satisfied by that lone €100,000 check.
Furthermore, it completely shields you from local wealth taxes and foreign asset reporting requirements, allowing you to reside in Milan or Florence while your global wealth remains entirely off the local grid.
3. The Full Exit: Zero-Bureaucracy Sovereign Relocation
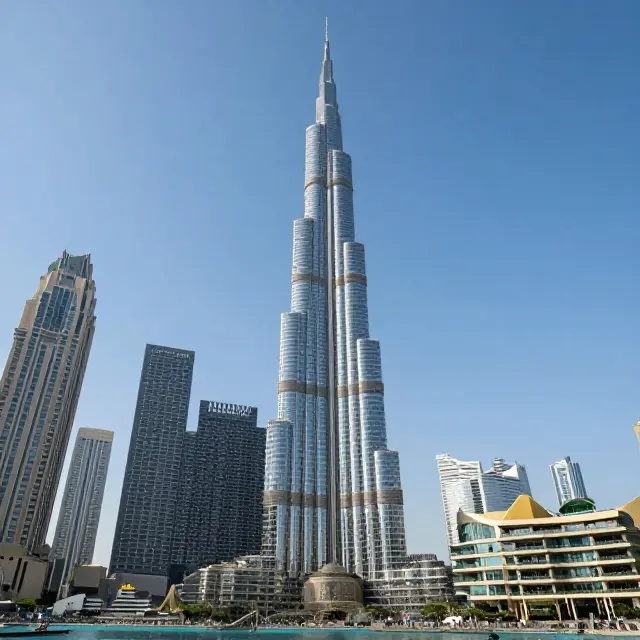
When the objective is a complete, permanent severance from European bureaucratic overreach, the entrepreneurial class is systematically shifting its operational and personal centers of gravity to zero-tax sovereign hubs, with Dubai (UAE) leading the migration.
- The Mechanics: By transitioning personal residency and business headquarters to the UAE, individuals permanently drop their personal income tax, capital gains tax, and wealth tax liabilities to 0%.
- The Practical Application: Unlike Europe, where an entrepreneur is buried under endless regulatory compliance, ESG mandates, and administrative friction, these jurisdictions are engineered for absolute operational velocity. It allows an independent innovator to liquidation-proof their assets, manage their holdings through highly secure international corporate structures, and regain absolute psychological and financial sovereignty over their life’s work.
Summary of Elite Relocation Frameworks
| Jurisdiction | Primary Mechanism | Best Suited For | Key Practical Advantage |
| Switzerland | Lump-Sum (Forfait) | Substantial Private Asset Holders | Taxes are based entirely on lifestyle expenses, leaving global portfolios completely untouched. |
| Italy | €100,000 Substitute Tax | Principals with High Foreign Income | A single flat fee completely covers all worldwide profits and wipes out local asset reporting. |
| Dubai (UAE) | 0% Sovereign Jurisdiction | Active Self-Made Capitalists | Complete elimination of wealth and income taxes coupled with zero corporate bureaucracy. |
The Uncompromised Vibe
This is the exact operational reality that separates the performative class from truly independent capital holders. True luxury is not found in expensive watches or flash hospitality; it is found in absolute discretion, unhurried peace of mind, and the structural freedom to ensure that your hard-earned enterprise belongs entirely to you—not the state.